

What Every New Build Buyer Should Know Before Completion
A mortgage offer on a new build can arrive with a line buyers don’t expect: part of the loan won’t be paid out at completion. That’s a retention, and estate agents almost never mention it before an offer’s accepted. Most people first hear the word when they’re already reading their own paperwork, which is not a great time to find out.
Resale houses barely ever come with this problem. What you’re buying is finished, so there’s nothing for a lender to withhold against. New builds are different because the site can still be part-finished on the day you get your keys.
Below: what causes a retention, what it costs you, which lenders you’re more likely to run into one with, and how to get the money released once you’re in. This guide goes deeper than our New Build Mortgages UK hub page, which only touches on retentions briefly.
What a mortgage retention actually is
Put simply, a retention is money the lender doesn’t hand over at completion. You still get the keys. You still move in on the date agreed. But a chunk of the loan sits with the lender until whatever’s outstanding, a piece of unfinished work, a missing certificate, gets sorted, usually inside a timeframe the lender sets when the offer’s made.
It isn’t aimed at the buyer and it isn’t a credit decision. A surveyor values the property, spots something that isn’t finished or confirmed, and flags it. The lender’s response is to protect the security they’re lending against by keeping back whatever the flagged item is worth until it’s fixed.
Why this only really happens on new builds
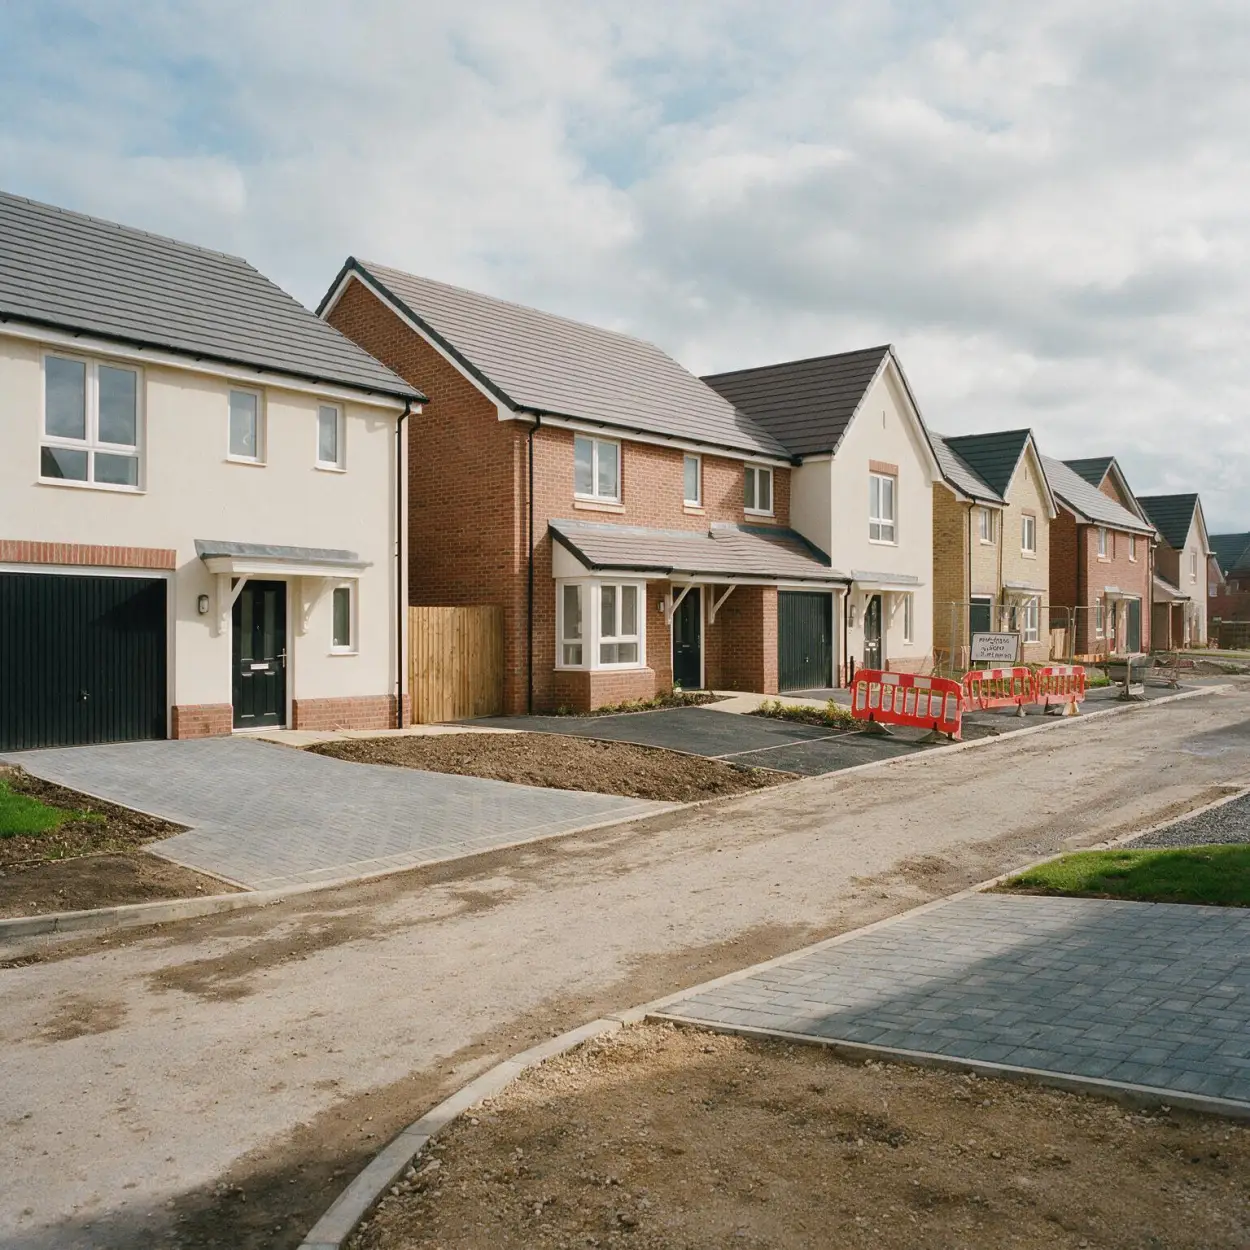
A RICS valuation on a resale property reflects what’s actually there. Paperwork and bricks match up. On a new build, they often don’t. A developer can hand over a house while the road serving it is still unadopted, the landscaping’s half-done, or a shared driveway across several plots hasn’t been laid yet. None of that makes a house unsafe to live in. It does mean part of what the surveyor priced in isn’t physically finished, and the retention exists to cover that gap.
What triggers a retention
Most retentions on new builds come from something outside the four walls: an unadopted road, footpaths not laid, bare-earth landscaping, or shared areas across a wider development that the builder hasn’t got to yet. On big phased sites this is common, because plots complete in waves while work continues on the ones further behind.
Inside the house, a retention is rarer but not unheard of. Damp, a boiler that’s not working properly, unfinished electrics, or a structural flag from the surveyor can all hold up funds until a specialist confirms the fix. Ordinary snagging, a scuffed skirting board, a door that sticks, paint touch-ups, almost never counts. Lenders care about value and safety. A punch list the developer will work through anyway doesn’t move the needle.
How much gets retained
There’s no formula tied to the purchase price. A small retention, £1,000 to £5,000, might cover an unfinished path or a certificate that hasn’t arrived. Several lenders won’t even chase anything under about £2,000; it costs more to administer than it’s worth holding back.
Bigger figures show up when the outstanding work is genuinely expensive, an unadopted road on a large site where the council’s own estimate runs into five figures, or a structural repair that needs a specialist before the lender will let go of the balance. In these cases the number tracks what the work actually costs, nothing more abstract than that.
Worked example: a £340,000 new build with a road retention
Here’s how it plays out on a real purchase. A buyer completes on a £340,000 three-bedroom new build. The road serving eight plots is still unadopted; the developer’s own quote for finishing the surfacing and drainage comes to £3,200. At completion the lender pays £336,800 and holds back £3,200, releasing it once the road work’s done and the council confirms adoption is under way.
Here’s the part buyers miss: interest is charged on the full £340,000 from day one, including the £3,200 sitting with the lender. On that amount, at a typical new build rate, it works out to roughly £12 a month for money the buyer never actually had. This purchase was arranged through our residential mortgage route.
Which lenders retain and which don’t
Not every lender behaves the same way, and it’s worth knowing before you pick a product rather than after your offer lands. TSB, Virgin Money, and a few smaller regional building societies tend to apply a retention whenever a surveyor flags something.
Others are more forgiving. HSBC, NatWest, Skipton, Leeds Building Society and several more will often wave through a small issue, generally under a couple of thousand pounds, without holding anything back. A smaller handful, Accord Mortgages and Precise Mortgages among them, rarely apply retentions at all as a matter of how they underwrite.
None of that is permanent. Policies shift, and what happens depends on the actual development and what’s outstanding on it. A broker who checks the site against current lender policy before you apply is how you avoid finding this out the hard way. Comparing current mortgage rates across lenders is worth doing alongside that check, since rate and retention appetite don’t always move together.
How the money gets released
Getting the money released is usually a paperwork exercise rather than a new application. A completion certificate, a council letter confirming road adoption, or a specialist’s sign-off on a repair covers most cases. On larger retentions, some lenders send a surveyor out to check in person before releasing anything; plenty of others are happy with documents alone.
Lenders are often more relaxed about this than people expect going in. A written quote for the remaining work, or a formal undertaking from the developer to finish it by a certain date, can be enough to get funds released even before the job’s actually done. It’s still worth chasing yourself. Retained money has sat unclaimed for months longer than it needed to simply because nobody followed up on it.
The interest you still pay
The interest point is worth repeating because it’s a real cost, not just a delay. You pay interest on the entire mortgage from completion, retained portion included, even though you never had that money in your account. On a £3,200 retention that’s around £12 extra a month, small in isolation, but it’s an avoidable cost most buyers only discover once they’ve started paying it.
What to do before exchange
Ask before you exchange. Is there likely to be a retention on this plot, and if so, what’s driving it? Site sales teams almost always know, especially on phased developments where road adoption timelines are common knowledge internally. Find this out early and you can budget for it, or push back on timing, instead of reading about it for the first time in your mortgage offer.
It’s worth getting a broker to check how your chosen lender treats retentions on that specific site before you apply. A lender likely to overlook a small, already-known issue versus one that automatically retains against it, that choice alone can be the difference between full funds on completion day and a wait of several months for money that was never really at risk.
If a retention does affect how much you can draw down on day one, it’s worth revisiting your affordability numbers with your broker so there are no surprises around what you can actually spend at completion.
Other new build costs worth planning for alongside a possible retention are covered in our guides to mortgage affordability and the different types of mortgage available in the UK.
Frequently Asked Questions
What actually is a mortgage retention on a new build?
Part of your agreed loan gets held back at completion, because the surveyor’s flagged something unfinished or uncertified, an unadopted road, say, or a missing warranty document, and it’s released once that’s sorted.
How much does one usually come to?
Smaller retentions sit between £1,000 and £5,000, tied to something specific like a footpath or landscaping. Bigger ones follow whatever the outstanding work actually costs rather than a set share of the purchase price.
Does every new build mortgage have a retention attached?
No. Most completions go through with the full amount paid on day one. It only becomes an issue when the surveyor flags a real problem, unfinished road, structural question, missing paperwork.
Which lenders are more likely to hold money back?
It shifts over time, but some lenders apply retentions fairly routinely once something’s flagged, while several major high street names and a couple of specialist lenders are known for letting small issues through. A broker checking current policy against your specific development beats guessing.
Do you keep paying interest on the part that's held back?
Yes, on the whole loan, retained amount included, from the day you complete. That money never reached your account, but you’re paying for it anyway, so it’s worth building into the budget.
How do you actually get a retention released?
Provide evidence the issue is fixed, a completion certificate, confirmation of road adoption, a specialist’s report. Some lenders send someone to check in person; others accept the paperwork alone. Chase it yourself rather than waiting for the lender to come to you.
Can this be found out before you exchange contracts?
Usually, if you simply ask. Developers and site sales teams know whether things like road adoption or landscaping are likely to trigger a retention on a given plot, and your broker can check how your particular lender tends to handle that.
Does having a retention change how much you can borrow in total?
No. The overall loan amount stays fixed. A retention only changes when part of it lands in your account, not the total sum you’re borrowing or how your affordability was worked out.
None of this is a reason to avoid a new build purchase. Plenty of completions happen without a retention ever coming up. What matters is knowing it’s possible before you exchange, having a rough sense of what it might cover if it does apply to your plot, and picking a lender whose approach to that specific development actually works for you rather than against you.
Speak to a new build mortgage specialist
If you’re not sure whether a retention is likely on your plot, or a lender has already flagged one on your offer, contact us today and we will check how your chosen lender treats retentions on that specific development before you commit to anything.
UK Mortgage Broker is a whole-of-market broker helping clients throughout the UK and globally to secure funding on UK property. We are directly authorised and regulated by the Financial Conduct Authority.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Call: +44 1628 969 500 Email: info@uk-mortgagebroker.co.uk
Related Pages
- New Build Mortgages UK – our main hub guide to new build mortgages, covering retentions, down-valuations, NHBC warranty and Help to Buy repayment.
- Residential Mortgages – whole-of-market advice for buying a home to live in, new build or resale.
- Mortgage Affordability UK – how lenders actually decide what you can borrow.
- Types of Mortgage UK – a full breakdown of the mortgage products available to UK buyers.
- Mortgage Rates UK – compare current rates across lenders before you apply.