New Build Mortgage Retentions Explained

Customer Support No Comments

What Every New Build Buyer Should Know Before Completion A mortgage offer on a new build can arrive with a line buyers don’t expect: part of the loan won’t be […]

Read More

What Every New Build Buyer Should Know Before Completion

A mortgage offer on a new build can arrive with a line buyers don’t expect: part of the loan won’t be paid out at completion. That’s a retention, and estate agents almost never mention it before an offer’s accepted. Most people first hear the word when they’re already reading their own paperwork, which is not a great time to find out.

Resale houses barely ever come with this problem. What you’re buying is finished, so there’s nothing for a lender to withhold against. New builds are different because the site can still be part-finished on the day you get your keys.

Below: what causes a retention, what it costs you, which lenders you’re more likely to run into one with, and how to get the money released once you’re in. This guide goes deeper than our New Build Mortgages UK hub page, which only touches on retentions briefly.


What a mortgage retention actually is

Put simply, a retention is money the lender doesn’t hand over at completion. You still get the keys. You still move in on the date agreed. But a chunk of the loan sits with the lender until whatever’s outstanding, a piece of unfinished work, a missing certificate, gets sorted, usually inside a timeframe the lender sets when the offer’s made.

It isn’t aimed at the buyer and it isn’t a credit decision. A surveyor values the property, spots something that isn’t finished or confirmed, and flags it. The lender’s response is to protect the security they’re lending against by keeping back whatever the flagged item is worth until it’s fixed.

Why this only really happens on new builds

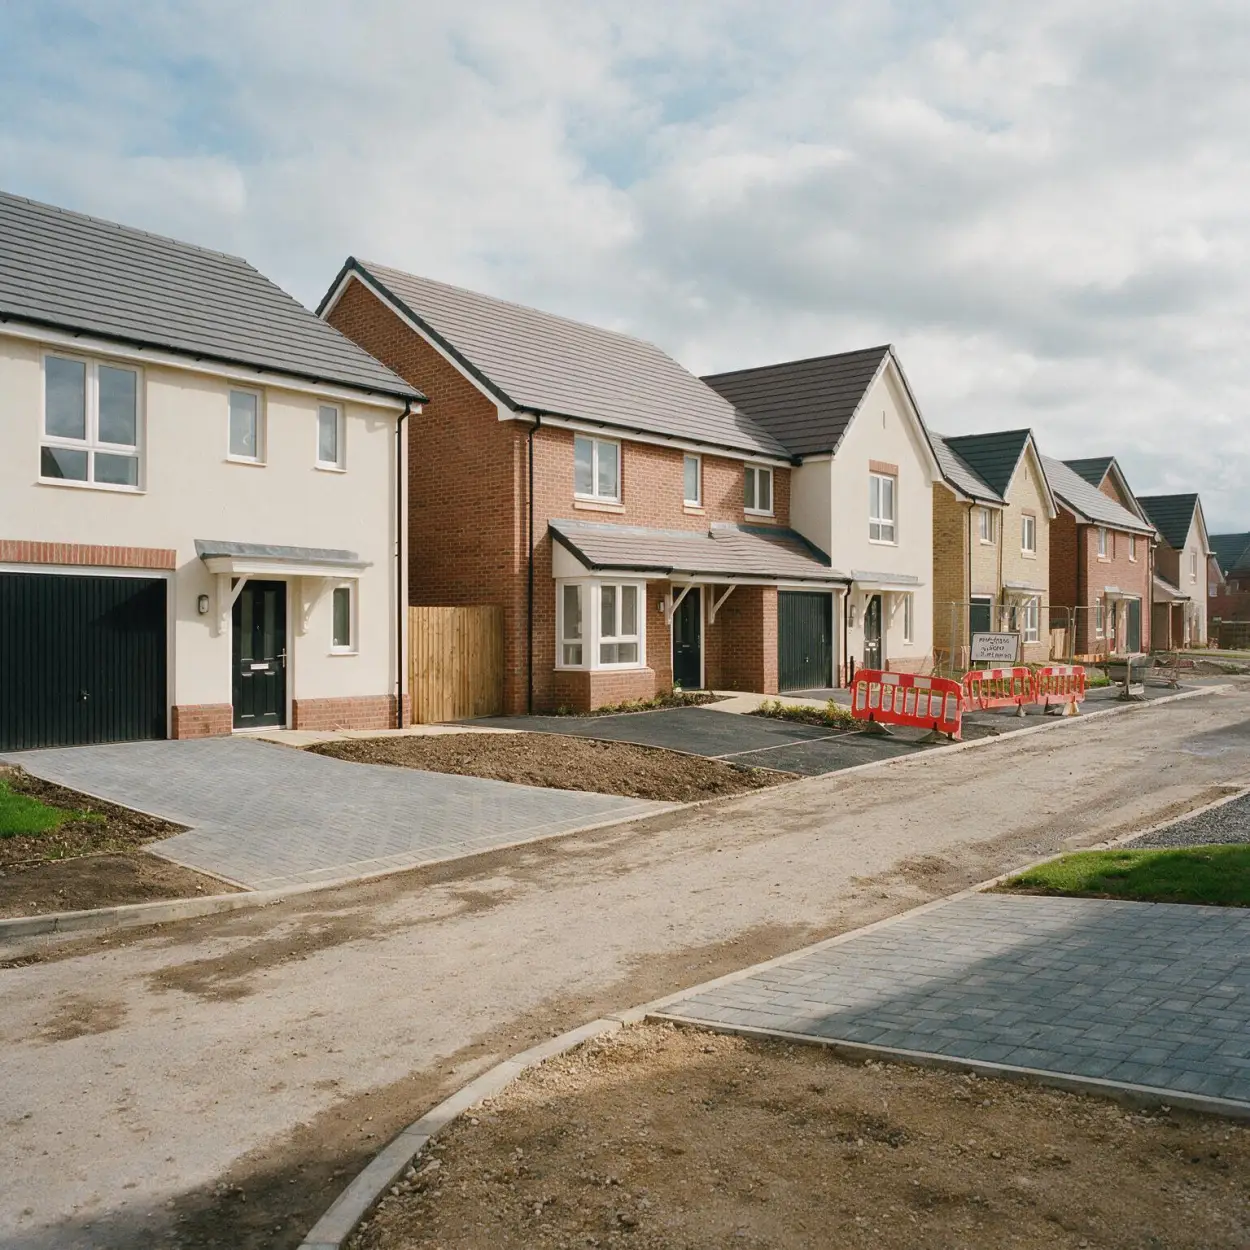
A RICS valuation on a resale property reflects what’s actually there. Paperwork and bricks match up. On a new build, they often don’t. A developer can hand over a house while the road serving it is still unadopted, the landscaping’s half-done, or a shared driveway across several plots hasn’t been laid yet. None of that makes a house unsafe to live in. It does mean part of what the surveyor priced in isn’t physically finished, and the retention exists to cover that gap.

What triggers a retention

Most retentions on new builds come from something outside the four walls: an unadopted road, footpaths not laid, bare-earth landscaping, or shared areas across a wider development that the builder hasn’t got to yet. On big phased sites this is common, because plots complete in waves while work continues on the ones further behind.

Inside the house, a retention is rarer but not unheard of. Damp, a boiler that’s not working properly, unfinished electrics, or a structural flag from the surveyor can all hold up funds until a specialist confirms the fix. Ordinary snagging, a scuffed skirting board, a door that sticks, paint touch-ups, almost never counts. Lenders care about value and safety. A punch list the developer will work through anyway doesn’t move the needle.

How much gets retained

There’s no formula tied to the purchase price. A small retention, £1,000 to £5,000, might cover an unfinished path or a certificate that hasn’t arrived. Several lenders won’t even chase anything under about £2,000; it costs more to administer than it’s worth holding back.

Bigger figures show up when the outstanding work is genuinely expensive, an unadopted road on a large site where the council’s own estimate runs into five figures, or a structural repair that needs a specialist before the lender will let go of the balance. In these cases the number tracks what the work actually costs, nothing more abstract than that.
UK mortgage offer and completion certificate used to release a new build mortgage retention
Evidence like a completion certificate is usually all that’s needed to get a retention released

Worked example: a £340,000 new build with a road retention

Here’s how it plays out on a real purchase. A buyer completes on a £340,000 three-bedroom new build. The road serving eight plots is still unadopted; the developer’s own quote for finishing the surfacing and drainage comes to £3,200. At completion the lender pays £336,800 and holds back £3,200, releasing it once the road work’s done and the council confirms adoption is under way.

Here’s the part buyers miss: interest is charged on the full £340,000 from day one, including the £3,200 sitting with the lender. On that amount, at a typical new build rate, it works out to roughly £12 a month for money the buyer never actually had. This purchase was arranged through our residential mortgage route.

Which lenders retain and which don’t

Not every lender behaves the same way, and it’s worth knowing before you pick a product rather than after your offer lands. TSB, Virgin Money, and a few smaller regional building societies tend to apply a retention whenever a surveyor flags something.

Others are more forgiving. HSBC, NatWest, Skipton, Leeds Building Society and several more will often wave through a small issue, generally under a couple of thousand pounds, without holding anything back. A smaller handful, Accord Mortgages and Precise Mortgages among them, rarely apply retentions at all as a matter of how they underwrite.

None of that is permanent. Policies shift, and what happens depends on the actual development and what’s outstanding on it. A broker who checks the site against current lender policy before you apply is how you avoid finding this out the hard way. Comparing current mortgage rates across lenders is worth doing alongside that check, since rate and retention appetite don’t always move together.


How the money gets released
New build homeowner shaking hands with site manager after mortgage retention work is completed
Once outstanding work is signed off, retained funds are usually released within weeks

Getting the money released is usually a paperwork exercise rather than a new application. A completion certificate, a council letter confirming road adoption, or a specialist’s sign-off on a repair covers most cases. On larger retentions, some lenders send a surveyor out to check in person before releasing anything; plenty of others are happy with documents alone.

Lenders are often more relaxed about this than people expect going in. A written quote for the remaining work, or a formal undertaking from the developer to finish it by a certain date, can be enough to get funds released even before the job’s actually done. It’s still worth chasing yourself. Retained money has sat unclaimed for months longer than it needed to simply because nobody followed up on it.

The interest you still pay

The interest point is worth repeating because it’s a real cost, not just a delay. You pay interest on the entire mortgage from completion, retained portion included, even though you never had that money in your account. On a £3,200 retention that’s around £12 extra a month, small in isolation, but it’s an avoidable cost most buyers only discover once they’ve started paying it.

What to do before exchange

Ask before you exchange. Is there likely to be a retention on this plot, and if so, what’s driving it? Site sales teams almost always know, especially on phased developments where road adoption timelines are common knowledge internally. Find this out early and you can budget for it, or push back on timing, instead of reading about it for the first time in your mortgage offer.

It’s worth getting a broker to check how your chosen lender treats retentions on that specific site before you apply. A lender likely to overlook a small, already-known issue versus one that automatically retains against it, that choice alone can be the difference between full funds on completion day and a wait of several months for money that was never really at risk.

If a retention does affect how much you can draw down on day one, it’s worth revisiting your affordability numbers with your broker so there are no surprises around what you can actually spend at completion.

Other new build costs worth planning for alongside a possible retention are covered in our guides to mortgage affordability and the different types of mortgage available in the UK.

Frequently Asked Questions

What actually is a mortgage retention on a new build?

Part of your agreed loan gets held back at completion, because the surveyor’s flagged something unfinished or uncertified, an unadopted road, say, or a missing warranty document, and it’s released once that’s sorted.

How much does one usually come to?

Smaller retentions sit between £1,000 and £5,000, tied to something specific like a footpath or landscaping. Bigger ones follow whatever the outstanding work actually costs rather than a set share of the purchase price.

Does every new build mortgage have a retention attached?

No. Most completions go through with the full amount paid on day one. It only becomes an issue when the surveyor flags a real problem, unfinished road, structural question, missing paperwork.

Which lenders are more likely to hold money back?

It shifts over time, but some lenders apply retentions fairly routinely once something’s flagged, while several major high street names and a couple of specialist lenders are known for letting small issues through. A broker checking current policy against your specific development beats guessing.

Do you keep paying interest on the part that's held back?

Yes, on the whole loan, retained amount included, from the day you complete. That money never reached your account, but you’re paying for it anyway, so it’s worth building into the budget.

How do you actually get a retention released?

Provide evidence the issue is fixed, a completion certificate, confirmation of road adoption, a specialist’s report. Some lenders send someone to check in person; others accept the paperwork alone. Chase it yourself rather than waiting for the lender to come to you.

Can this be found out before you exchange contracts?

Usually, if you simply ask. Developers and site sales teams know whether things like road adoption or landscaping are likely to trigger a retention on a given plot, and your broker can check how your particular lender tends to handle that.

Does having a retention change how much you can borrow in total?

No. The overall loan amount stays fixed. A retention only changes when part of it lands in your account, not the total sum you’re borrowing or how your affordability was worked out.

None of this is a reason to avoid a new build purchase. Plenty of completions happen without a retention ever coming up. What matters is knowing it’s possible before you exchange, having a rough sense of what it might cover if it does apply to your plot, and picking a lender whose approach to that specific development actually works for you rather than against you.

Speak to a new build mortgage specialist

If you’re not sure whether a retention is likely on your plot, or a lender has already flagged one on your offer, contact us today and we will check how your chosen lender treats retentions on that specific development before you commit to anything.

UK Mortgage Broker is a whole-of-market broker helping clients throughout the UK and globally to secure funding on UK property. We are directly authorised and regulated by the Financial Conduct Authority.

Your home may be repossessed if you do not keep up repayments on your mortgage.

Call: +44 1628 969 500 Email: info@uk-mortgagebroker.co.uk

Related Pages

Bad Credit Mortgages in 2026: Remortgage or Second Charge to Consolidate Debt

Customer Support No Comments

Where the market stands for adverse-credit borrowers right now, and how to fold existing debt into a remortgage or second charge. Missed a few payments? Got a default or a […]

Read More

Where the market stands for adverse-credit borrowers right now, and how to fold existing debt into a remortgage or second charge.

Missed a few payments? Got a default or a CCJ on your file? Heading into the back half of 2026, the picture is calmer than it has looked in years. Arrears have come down, lenders want the business, and there are more ways for people with patchy credit to sort out their finances than there have been in a long time. What has really shifted, though, is how borrowers deal with the debt they have already run up. More and more are turning to a remortgage, or a second charge mortgage, to pull it into one place. Here is where things stand for adverse-credit borrowers this year, and how debt consolidation actually works when your credit file has a few marks on it.


The 2026 picture: how are adverse-credit borrowers doing?

Start with the numbers, because they tell a better story than the last couple of years of headlines. UK Finance counted 79,110 homeowner mortgages in arrears in the first quarter of 2026. That is 2% fewer than the quarter before, and the lowest the figure has been for three years. On the buy-to-let side the drop was steeper still, down 24% on the same point last year. Repossessions stayed rare, and UK Finance makes the point that most of them, more than two in three, involved mortgages taken out at least a decade ago.

None of that means people feel comfortable. UK Finance itself describes the backdrop as fragile, and the Bank of England has kept base rate at 3.75% all year, holding it again on 30 July for the fifth time running. With no cut on the horizon, waiting for rates to rescue the monthly budget is not much of a plan. So a lot of borrowers are simply getting on and reorganising what they owe.

Why so many people are consolidating debt in 2026

You can see it most clearly in second charge lending, which has taken off. The Finance & Leasing Association put second charge lending at £625m for the first quarter of 2026, a third higher than a year earlier, across 11,489 new agreements. Over the full year to March, borrowers took out £2.3bn of it. The sector has not been this busy in roughly 18 years, and the reason lenders and packagers keep giving is the same one: people are clearing other debts.

Why now? Plenty of homeowners locked in a cheap mortgage rate a few years back and have no intention of giving it up. Folding credit cards, personal loans and car finance into a single secured payment can bring the monthly total down and swap a handful of higher-rate bills for one you can actually plan around. For someone whose credit has started to slip, it can be a way to steady things before they get worse. The catch is in the detail. Turning unsecured debt into debt secured on your home is not a decision to take lightly, and it only works with the right structure behind it.

Remortgage or second charge? The two routes to consolidate

There are really two ways to raise money against your property to clear other debts, and which one suits you comes down mostly to the rate you are already paying.

Hands holding house keys above mortgage paperwork and a calculator, illustrating a second charge mortgage or remortgage
A second charge sits behind your existing mortgage, so your original rate stays untouched

Remortgaging means replacing your current mortgage with a bigger one and using the extra to pay off what you owe elsewhere. If your existing deal is ending anyway, or it is no cheaper than what is on offer now, this is often the tidiest option. The problem comes when you are sitting on a low fixed rate. Remortgage the whole balance and you lose that rate across all of your borrowing, and the extra interest on the lot can easily swallow whatever the consolidation saved.

A second charge works differently. It sits behind your existing mortgage as a separate loan, so the original deal, and its rate, carries on untouched. You pay the second charge rate on the new money only, not on everything. That is the whole appeal, and it is why second charge lending has jumped this year: you get to consolidate without handing back a cheap first-charge rate. Second charge lenders also tend to be more relaxed about adverse credit than a high street remortgage, because difficult cases are what they handle all day.

Can you remortgage to consolidate debt with bad credit?

Yes. Bad credit does not shut the door, though it does shrink the number of lenders who will say yes. The high street runs everything through automated scoring, and a recent default, a CCJ or a run of missed payments will often get a remortgage turned down flat. Specialist lenders work another way. They want the context: when the problem happened, whether it has been settled, what caused it, and how things look for you now. A default from three years ago that has since been cleared sits in a completely different place to a payment you missed last month.

Two things carry as much weight as the credit history itself. One is how much equity you hold. The other is whether you can afford the new payment. More equity, meaning a lower loan-to-value, gives the lender a bigger safety margin and opens up more of the market. And because consolidating adds to what is secured on the property, the lender has to be sure the larger payment is one you can genuinely keep up. Before you apply, it is worth working out how much you can borrow and taking an honest look at your affordability.

When a second charge makes more sense

Three situations usually point towards a second charge. The first is when you are tied to a low fixed rate you would be mad to give up. The second is when your current lender simply will not lend you any more. The third is when recent credit trouble means a full remortgage would either be declined or come at a punishing rate. Because the second charge only touches the new borrowing, the sums often beat remortgaging the whole balance onto a higher rate, even though the second charge rate on its own looks dearer than a standard first-charge deal.

What you are trading off is that you will be running two secured loans against the home at once, and the debt usually gets stretched over a longer period than the original loans or cards would have been. Your monthly cost drops, but left alone the total can climb, so overpaying where the deal lets you is worth doing. Weighing that up is exactly where a broker earns their keep. Our page on the true cost of a mortgage shows how stretching the term changes the maths.

What lenders look at

    • The credit issue itself – a default, CCJ, missed payment, IVA, debt management plan or bankruptcy each get handled differently, and how recent it is counts for more than what it is called.
    • Loan-to-value – the more equity behind the loan, the more lenders in play and the sharper the pricing; pile on a lot of consolidation at a high LTV and the options thin out fast.
    • Whether the new payment is affordable – the lender has to see that the bigger secured payment fits your income and what you already owe.
    • Whether it actually helps – a decent lender, and a decent broker, will only go ahead if you come out better off, not just staring at a smaller monthly number.

How a broker helps

Getting this right, remortgage or second charge, and finding the lender who will approve you rather than the one who will not, mostly comes down to knowing the market. We are whole-of-market, so we place adverse-credit cases with the specialist lenders who look at the person and not just the score. We will run both routes side by side so you can see what each really costs before you commit to either. If a straightforward bad credit mortgage is the smarter move, we will say so. If a second charge lets you hang on to a cheap rate, we will put the numbers in front of you. The aim does not change: you finishing up better off than you started.


Frequently Asked Questions

Can I consolidate debt with a mortgage if I have bad credit?

In most cases yes, though it usually means a specialist lender rather than the high street. Bad credit narrows your choices, it does not remove them. A specialist looks at what went wrong and when, alongside where your finances sit today, instead of rejecting you on a score alone.

Is a remortgage or a second charge better for debt consolidation?

That hinges on the rate you are already on. Sitting on a low fixed rate? A second charge lets you consolidate and keep it. Coming off your deal, or paying over the odds already? A full remortgage might work out cheaper.

Will consolidating debts into my mortgage lower my monthly payments?

Most of the time it will, but there is a trade-off. Spreading a short-term debt across a much longer mortgage term cuts the monthly figure while adding to what you pay in total, unless you overpay when your deal allows it.

How recent can a default or CCJ be and still get a mortgage?

There is no fixed cut-off; timing and circumstances do the talking. A default from a few years back that you have since settled reads very differently to a payment missed last month. Every specialist lender draws the line in its own place.

Does a second charge affect my existing mortgage?

No, your first mortgage carries on exactly as it is, rate and all. The second charge is a separate loan that sits behind it, so you keep your current deal and pay the new rate on the extra you borrow only.

How much equity do I need to consolidate debt against my home?

The more, the better. A lower loan-to-value gives the lender more comfort, brings more lenders into play and earns you a sharper rate. Try to consolidate a large sum at a high LTV and it gets harder to place.

Are second charge mortgages regulated?

Regulated ones fall squarely under FCA rules. They come with the same protections as a first-charge residential mortgage, advice and affordability checks included.

Should I get advice before consolidating debt into my home?

Yes – moving debt that was unsecured onto your home is a big step. A broker can line up the remortgage and second charge routes against each other, sanity-check that you will actually be better off, and get the case to the right lender.

Think carefully before securing other debts against your home. Consolidating debts into a mortgage or second charge may reduce your monthly payments but can increase the total amount you repay over the term. Your home may be repossessed if you do not keep up repayments on a mortgage or any other debt secured on it.

Mortgage advisor smiling on the phone at his desk, ready to discuss bad credit and debt consolidation options
Speak to a bad credit and debt consolidation specialist

Speak to a bad credit and debt consolidation specialist

If you are weighing up whether to remortgage or take a second charge to consolidate debt, contact us today and we will talk you through both routes, your likely rate and loan-to-value, and how best to structure the application before anything is submitted.

UK Mortgage Broker is a whole-of-market broker helping clients throughout the UK and globally to secure funding on UK property. We are directly authorised and regulated by the Financial Conduct Authority.

Your home may be repossessed if you do not keep up repayments on your mortgage.

Call: +44 1628 969 500 Email: info@uk-mortgagebroker.co.uk

Related Pages

Interest-Only Mortgages Returning for First-Time Buyers

Customer Support No Comments

Interest-only mortgages have been making a comeback – and this time there is a big focus on helping first-time buyers. It became much harder for first mortgage seekers to get […]

Read More

Interest-only mortgages have been making a comeback – and this time there is a big focus on helping first-time buyers. It became much harder for first mortgage seekers to get interest-only mortgages after the 2008 economic crash, but things have gradually been evolving and you may well be able to now secure one if you are a first-time buyer with a larger deposit.

If you are ready to find out more about the pros, cons, risks and why this change is so important for many first time buyer mortgages in the United Kingdom, then read on.

Why Have Interest-Only Mortgages Come Back?

Until recently, interest only mortgage deals were out of reach for most non-buy-to-let borrowers. The financial crash in 2008 meant lenders became much more cautious about this kind of borrowing. Affordability stress tests have been loosened by the FCA and this has encouraged lenders to reintroduce more flexible options. This means interest-only mortgages are not just for landlords and similar investors anymore, they are increasingly accessible for first-time buyers.

Mortgage lenders are becoming more flexible with interest-only mortgages as they recognise that not every borrower needs a full repayment deal, especially if they are likely to relocate in a few years. For some first-time buyers, interest-only borrowing can be a smart short-term solution that frees up monthly cash without them having to commit to a long-term repayment agreement.

The key difference between today’s interest-only mortgages and those of the past is accountability. Lenders now expect to see a clear, credible repayment strategy right away, and borrowers need to take a more proactive approach to planning how they will repay the loan at the end of the term.

First-time buyer reviewing an interest-only mortgage repayment plan with an adviser


What Are the Benefits of Interest-Only Mortgages for First-Time Buyers?

As you will only be paying the interest on the loan, your monthly outgoings will be lower so you can free up cash. As the balance will not be going down, you can clear it by selling your property later or with another repayment plan.

When you are making lower payments than you would with a traditional mortgage, you might qualify for a bigger loan or be able to buy a better property than you normally would. The extra funds you will have access to due to an interest-only mortgage can be used for things like home improvements, savings and investments.

What Are the Disadvantages of Interest-Only Mortgages for First-Time Buyers?

You will need a firm plan to repay the money once the mortgage term ends as you will still owe the full amount that you originally borrowed. You could be in trouble if you cannot pay it back. These mortgages can also be more expensive over time if you are paying more interest than you otherwise would.

Lenders also tend to have stricter criteria when it comes to interest-only loans. You will normally need a minimum deposit of at least 20-25%, income of £50,000 or more and proof that you will be able to repay the money at the end of the term. If you want to use your property or other investments to repay, you could find yourself in trouble if these do not see as much growth as you expect.

Creating a Strong Repayment Strategy for an Interest-Only Mortgage

If you want to apply for an interest-only mortgage, you will need a solid plan that you can show lenders upfront.

You may plan to use:

  • Savings or Investments

This means building up enough money over time using savings accounts, ISAs, shares or a pension. These can ensure you have a lump sum to clear the debt at the end.

  • Rising Property Values

Some buyers expect their homes to increase in value so they can sell them later and use the profit to pay off the mortgage. Although this can work, nothing is guaranteed when it comes to future property values. You may also plan to remortgage once the deal ends.

Another option could be to opt for a hybrid mortgage, paying off some of the loan gradually and the rest at the end of the term. This can reduce the final lump sum you pay. Hybrid mortgages are often also referred to as “Part and Part Mortgages” – as part of the mortgage is interest only and part is capital repayment.

Whatever the case, lenders will want to see a realistic and achievable plan, not something that is mainly based on hope.

Check out our First Time Buyer Mortgage Calculator today to see how much your monthly mortgage payments will be and how much you can borrow.

Should I Consider an Interest-Only Mortgage as a First-Time Buyer?

An interest-only mortgage is more likely to be right for you if you have a large deposit of at least 20-25%. You will need a strong repayment plan and to clearly understand the terms. It may not be the best solution if your repayment plan is not convincing enough, you are relying on uncertain market growth and you do not want the pressure of finding a large sum by the end of the agreement.

How a UK Mortgage Broker Can Help

Getting an interest-only mortgage when you are a first time buyer can be complicated. You will have stricter eligibility rules to meet, a smaller range of deals and more risk if you get it wrong. This is why so many first time borrowers are using UK mortgage brokers to get the right deals for their specific needs.

One of the best reasons for getting help from a mortgage broker is that they work for you rather than the bank. They can examine the entire market and find lenders who do not usually advertise to the public. This helps them to find deals which are right for your deposit size, your income and your long-term plans. The best mortgage brokers know which lenders are currently accepting interest-only first-time buyer applications, and they know which types of repayment strategies lenders are likely to accept.

Another great reason for using a mortgage broker when you need an interest-only mortgage as a first-time buyer is they can help you curate all the essential documents that you will need to impress lenders. They will use their experience and expertise to present your application in a way that matches all lender expectations. This will boost your chances of being approved.

Interest-only mortgages are less common than standard repayment deals, so it can really help to have an expert on your side who can explain all the terms to you clearly to prevent confusion. Their help can prevent you from missing out on the best deals or being stuck with an unsuitable agreement. When you use a broker, you have a great chance of getting the ideal mortgage for your situation.

Couple discussing interest-only mortgage options with a UK Mortgage Broker adviser


Why Choose Us When You Need the Best Deal on an Interest-Only Mortgage

At UK Mortgage Broker, we are proud to be one of the UK’s leading and most reliable mortgage brokers. We are a whole-of-market broker with access to a huge range of lenders. This is why we have been able to help thousands of people seeking specialist interest-only deals that were not advertised to the general public. We are here to identify the best deals for your income, deposit size and long-term repayment strategy.

As we are not tied to any specific lender, you can rest assured that our advice will always be tailored to your best interests. We know how hard it can be to get on the property ladder and can use our vast experience to guide you every step of the way, whether you need help breaking down complex financial language or coming up with a credible repayment plan.

When you have the support of first time buyer mortgage experts, it becomes so much easier to find a deal you will not come to regret later. Choose us to make the UK mortgage application process so much more straightforward and manageable.

Interest-only mortgages are nothing new, but they are now certainly making things easier for some first-time buyers after being much harder to access for well over a decade. However, the terms tend to be much stricter than they were in the past. You will not only need a bigger deposit but your exit strategy will also need to be stronger and more convincing than the repayment plans put forward by borrowers years ago.

Explore Your Options

In a world where even starter homes cost six figures and living costs are still putting lots of pressure on household incomes, an interest-only mortgage can be the only way onto the property ladder for some first-time buyers.

If you are in the process of weighing up your mortgage options, consider speaking to a UK mortgage broker who can work around your specific situation. A broker can help you find deals that you will struggle to get from High Street banks. They can identify solutions that are ideal for your circumstances.

Frequently Asked Questions

Can first-time buyers get an interest-only mortgage in the UK?

They can, though it is a genuinely small corner of the market compared to five years ago.
We have placed interest-only deals for first-time buyers with the right deposit size, but the criteria are noticeably tighter than they were before 2008 – lenders want a proper answer for how you will repay the capital, not just an intention.

How big a deposit do I need for an interest-only mortgage as a first-time buyer?

Expect to be asked for somewhere in the 20-25% region, sometimes more depending on the lender and your income.
That is a substantial jump from what a repayment mortgage might ask for, which is part of why interest-only tends to suit buyers who already have savings or investments behind them rather than those stretching for their first deposit.

What counts as an acceptable repayment strategy?

Something concrete a lender can actually assess – savings or investment accounts building towards a target figure, a documented plan to downsize or sell, or a hybrid arrangement where part of the loan is on repayment terms.
What will not fly is house prices probably going up with nothing behind it.

What is a Part and Part mortgage?

Part and Part splits your mortgage between interest-only and repayment, so the balance ticks down slowly instead of staying flat for the whole term.
A client of ours a few months back wanted the lower payments of interest-only but did not love the idea of still owing £280,000 in twenty-five years – roughly 60% of their loan went on interest-only, the rest on repayment. Not every lender offers it, but where it is available it is worth asking about.

Is an interest-only mortgage riskier than a repayment mortgage?

Riskier is fair, yes, but the risk sits in a different place – with interest-only, it shows up right at the end when the loan matures and the full amount is still due.
With repayment, missing monthly payments is the danger; with interest-only it is reaching the end of the term with no way to clear the balance. We have seen it go wrong for people who assumed rising house prices alone would cover it – that is why we push clients hard on having an actual plan, not a hope.

Why would a broker help more than going straight to a bank?

Because most high-street banks only offer their own products, and interest-only for first-time buyers is not something every lender advertises openly.
We can look across the whole market, including lenders who take a more flexible view of repayment strategies, and match you to whoever is actually right for your situation.

Speak to an Interest-Only Mortgage Specialist

If you are weighing up whether interest-only is right for your first purchase, the honest answer is that it depends entirely on your deposit, your income and how solid your repayment plan is. Our advisers will talk you through what lenders are actually looking for right now and whether it genuinely fits your situation, rather than assuming it does because it sounds cheaper month to month.

UK Mortgage Broker is a whole-of-market broker helping clients throughout the UK and globally to secure funding on UK property. We are directly authorised and regulated by the Financial Conduct Authority.

Your home may be repossessed if you do not keep up repayments on your mortgage.

Call: +44 1628 969 500 Email: info@uk-mortgagebroker.co.uk

Related Pages

First Time Buyer Home Ownership Schemes

Customer Support No Comments

Unlock the door to your dream home with our guide, “Help to Buy and Beyond!” In this short video, we’ll delve into the essentials of the Help to Buy Scheme, […]

Read More

Unlock the door to your dream home with our guide, “Help to Buy and Beyond!”

In this short video, we’ll delve into the essentials of the Help to Buy Scheme, how it can pave your way to homeownership, and what steps to take next, especially if you’re a First Time Buyer. Featuring expert tips, you’ll learn how to navigate the housing market with ease.

Shared Ownership in the UK – Ultimate Guide for First time Buyers

Customer Support No Comments

Discover how Shared Ownership can make your dream of owning a home a reality! In this video, we break down the concept of Sharetobuy, explaining how it works and how […]

Read More

Discover how Shared Ownership can make your dream of owning a home a reality!

In this video, we break down the concept of Sharetobuy, explaining how it works and how you can buy a share of a property while paying rent on the rest.

Learn about the steps to apply for First time Buyers, including eligibility criteria and finding the perfect property. Explore the benefits, such as affordability, lower deposits, and a clear pathway to full ownership.

Mortgage Broker UK offer whole-of-market search with totally FREE mortgage quotes and advice, so Contact Us today.

How Your Credit Score Impacts Your Mortgage

Customer Support No Comments

Your credit score can Make or Break your mortgage deal! A good credit score means lower interest rates and better terms. Lenders use your credit score to decide how much […]

Read More

Your credit score can Make or Break your mortgage deal!

A good credit score means lower interest rates and better terms. Lenders use your credit score to decide how much they’re willing to lend and at what rate.

It’s not just about the score though. They also look at your income, expenses and other debts.

Want to boost your credit score – this video shows you how!

UK Mortgage Broker offer whole-of-market search with totally FREE mortgage quotes and advice, so Contact Us today.

How to Get a Mortgage if You’re Self Employed

Customer Support No Comments

With the right help, it’s easier than you think to get a Mortgage if you’re Self-employed! Getting a mortgage as a self-employed individual in the UK might seem tricky, but […]

Read More

With the right help, it’s easier than you think to get a Mortgage if you’re Self-employed!

Getting a mortgage as a self-employed individual in the UK might seem tricky, but it’s Totally doable with the right help and support.

In this video, we cover the main items you need to allow for and Lenders will need to see in order to secure a Self-employed Mortgage.

UK Mortgage Broker offer whole-of-market search with totally FREE mortgage quotes and advice, so Contact Us today.

Right to Buy Scheme UK – All You Need to Know

Customer Support No Comments

The Right to Buy Scheme is a fantastic way of helping British Council Tenants get on property ladder. The Scheme was released back in the 1980s and enables Council Tenants […]

Read More

The Right to Buy Scheme is a fantastic way of helping British Council Tenants get on property ladder.

The Scheme was released back in the 1980s and enables Council Tenants who have been been renting from the council for at least 3 years to not only buy their council home, but also get a DISCOUNT of up to 70% of the property’s value!

The amount of the discount is capped at £87,200 outside London and £116,200 in the capital. In this video, we give you all the information you need to know about the Right to Buy Scheme and what the exact process is for you to make an application yourself, if you wanted to buy your own Council Property so you can become a homeowner yourself!

In this video, we give you all the information you need to know about the Right to Buy Scheme and what the exact process is for you to make an application yourself, if you wanted to buy your own Council Property so you can become a homeowner yourself!

UK Mortgage Broker offer whole-of-market search with totally FREE mortgage quotes and advice, so Contact Us today.

Navigating the UK Mortgage Market in 2024: What You Need to Know

Customer Support No Comments

Buying a home in the UK remains a dream for many, but navigating the current mortgage market can feel like sailing through turbulent waters. Interest rate hikes, a cooling market […]

Read More

Buying a home in the UK remains a dream for many, but navigating the current mortgage market can feel like sailing through turbulent waters. Interest rate hikes, a cooling market and economic uncertainty have many asking: is now the right time to buy a UK property in 2024? While there are undeniable challenges, opportunities still exist for savvy borrowers. In this post, we’ll explore the current state of the UK mortgage market, offering insights and guidance for potential buyers, existing homeowners and those considering remortgaging.

Market Overview: Shifting Tides

The past year saw major shifts in the UK mortgage market. Following a period of historically low interest rates, the Bank of England began raising rates in December 2021 to combat inflation. This resulted in:

  1. Higher mortgage rates
    The average two-year fixed rate currently stands at 5.58%, while five-year deals average 5.22%. While these represent a slight decrease from peaks earlier in 2024, they remain considerably higher than pre-2022 levels.
  2. Mortgage lending decrease
    UK Finance predicts a fall in mortgage lending in 2024, with remortgaging activity anticipated to decline after a peak in maturing fixed-rate deals.
    Increased pressure on homeowners: Rising living costs combined with higher mortgage payments could strain finances for some homeowners.
  3. Challenges and Opportunities for BorrowersThis evolving landscape presents both challenges and opportunities for different borrower segments:
  • First-time buyers: Higher entry barriers due to stricter affordability checks and larger deposits required. However, a cooling housing market might present lower property prices, offering some balance.
  • Existing homeowners: Remortgaging to secure a better deal can be beneficial, especially for those currently on expiring low-interest fixed rates. However, careful budgeting is crucial due to higher monthly payments.
  • Buy-to-let investors: Stricter lending criteria and lower rental yields make buy-to-let less attractive. Alternative investment options should be explored.

Get in touch with Mortgage Broker UK today to discuss your Residential, First-time Buyer, Contractor and Buy to Let Mortgage requirements.

Key Considerations for Navigating the Market

  • Affordability: Conduct thorough budgeting to ensure you can comfortably afford monthly repayments with higher interest rates.
  • Deposit size: Aim for a larger deposit to reduce borrowing and secure better mortgage rates.
  • Fixed vs. variable rates: Weigh the stability of fixed rates against the potential flexibility of variable rates, considering your risk tolerance and financial goals.
  • Seek professional advice: A mortgage advisor can guide you through the complexities of the market, matching your needs with the most suitable products and lenders.

Beyond the Headlines: Hope on the Horizon

While the UK mortgage market faces challenges, positive developments offer hope for potential buyers and homeowners. Consider the following key points:

  • Mortgage rate stabilisation
    While interest rates remain higher than in recent years, they appear to be stabilising after initial hikes and it is highly predicated that the Bank of England base rate has now peaked after multiple months of no additional increases.
  • Government support schemes
    Initiatives like the Mortgage Guarantee Scheme can aid first-time buyers with smaller deposits.
  • A cooling housing market
    Potential house price softening in some areas of the UK could make property more affordable.

Crucially, the UK mortgage market is very dynamic and circumstances can change quickly. Staying informed, conducting thorough research and seeking professional advice are crucial for making informed decisions in this evolving landscape.

UK Mortgage Broker offer whole-of-market search with totally FREE mortgage quotes and advice, so Contact Us today.

Read about the UK Housing Market via our Specialist Residential & Buy to Let Division

First-Time Buyers in the UK Property Market: When is the Right Time to Buy?

Customer Support No Comments

Purchasing a property for the first time can be both exciting and daunting. As a first-time buyer in the UK property market, it’s crucial to consider various factors before making […]

Read More

Purchasing a property for the first time can be both exciting and daunting. As a first-time buyer in the UK property market, it’s crucial to consider various factors before making this significant financial commitment. Timing plays a crucial role in ensuring a successful purchase. In this article, we will explore the optimal conditions for first-time buyers, helping you determine when is the right time to take the leap into homeownership.

Market Conditions

The UK property market is subject to fluctuations, making it essential for first-time buyers to monitor market conditions. Historically, low-interest rates tend to favor buyers, as they can secure favorable mortgage terms. Additionally, a buyer’s market, characterized by a surplus of properties and reduced competition, can provide excellent opportunities for first-time buyers to negotiate better deals.

Conversely, during a seller’s market, where demand exceeds supply, prices tend to increase, making it more challenging for first-time buyers to enter the market. Staying up to date with market trends and consulting with professionals, such as estate agents and mortgage brokers, can help you determine whether it’s a favorable time to buy.

First Time Buyer Mortgage

Financial Preparedness

Before purchasing your first property, it’s crucial to assess your financial readiness. Consider saving for a deposit, as a larger deposit will enable you to secure a better mortgage rate. Saving for other associated costs, such as legal fees, surveys, and moving expenses, is also essential.

Furthermore, reviewing your credit score is vital, as it affects your ability to secure a mortgage. Ensure you have a good credit history and take steps to improve it if necessary. This will increase your chances of obtaining a mortgage with favorable terms.

Government Schemes and Incentives

The UK government has introduced various schemes and incentives to support first-time buyers. These initiatives aim to make homeownership more accessible, particularly for those struggling to save for a deposit. Researching and taking advantage of these schemes can significantly benefit first-time buyers.

Best first time buyer mortgage broker

Some popular schemes include Help to Buy, Shared Ownership, and the Lifetime ISA. Help to Buy offers equity loans, allowing buyers to borrow up to 20% (40% in London) of the property’s value, interest-free for the first five years. Shared Ownership enables buyers to purchase a share of a property and pay rent on the remaining portion. The Lifetime ISA provides a government bonus of up to £1,000 per year towards a first home.

Personal Circumstances

Every individual’s circumstances are unique, and it’s essential to consider personal factors when determining the right time to buy. Consider stability in your job or career, as a steady income will increase your chances of securing a mortgage. Additionally, evaluate your long-term plans, such as starting a family or relocating, as these factors may influence your decision.

Conclusion

Timing is crucial for first-time buyers in the UK property market. By monitoring market conditions, ensuring financial preparedness, exploring government schemes, and considering personal circumstances, you can make an informed decision on when the right time is to take your first step towards homeownership.

Remember, consulting with professionals in the industry will provide invaluable guidance tailored to your specific situation.

UK Mortgage Broker are highly experienced in working with First Time Buyers so Contact Us today for totally FREE quote and no-obligation advice.